Atlanta and Georgia Injury Claims
The Crash Wasn't Your Fault. So Who Pays?
A plain-language guide to how insurance works after a serious injury, from the at-fault driver's policy to your own coverage and your medical bills.
By Adanna Ugwonali · Published October 20, 2026
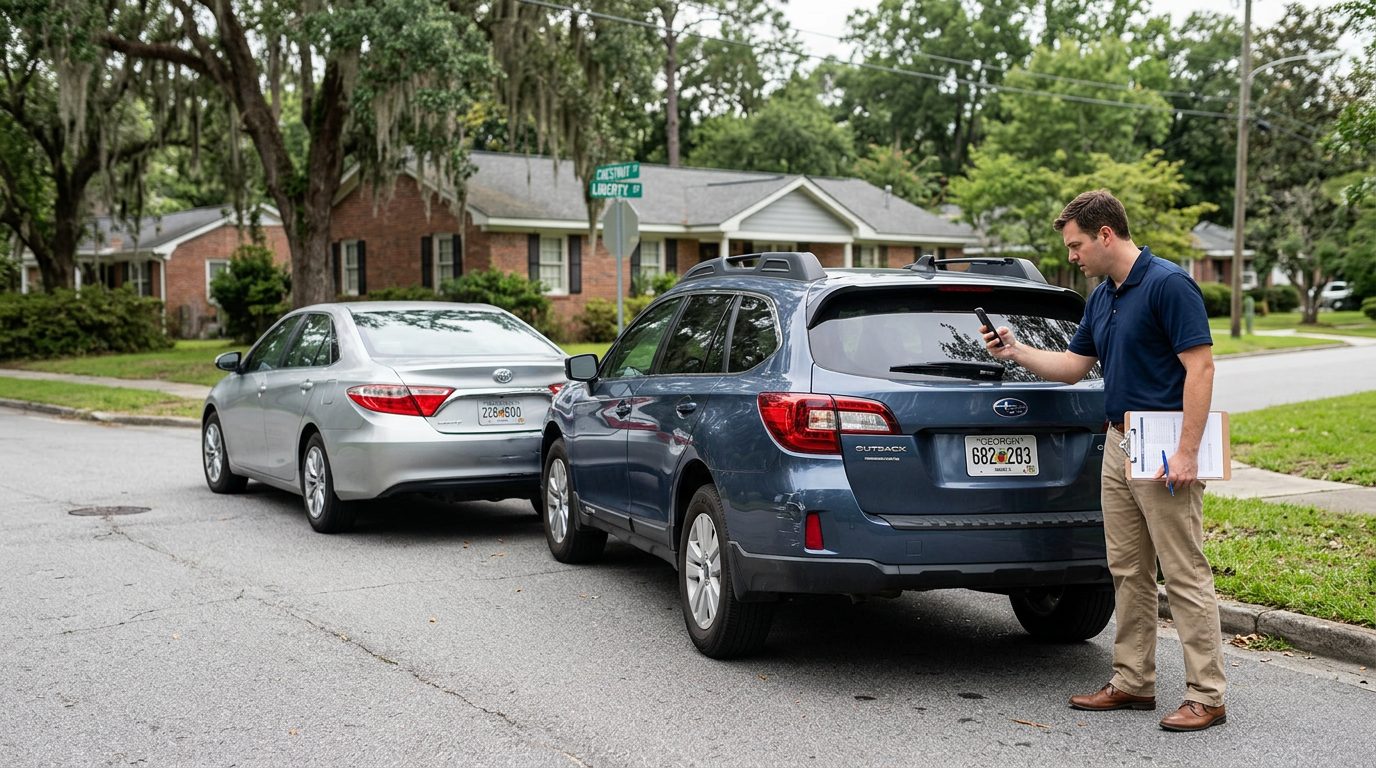
If you were hurt in a crash or fall someone else caused, the at-fault party’s liability insurance is usually the main source of payment. How does insurance work if it’s not your fault? In Georgia, that coverage pays for the harm the at-fault person caused, and your own policy may still help with your car and some bills. This guide explains each piece for people with serious injuries that need real medical care, such as fractures, hospital stays, brain or spinal injuries, and wrongful death.
The Short Answer for Georgia Drivers
Georgia injury claims are built on fault, so the at-fault party’s liability insurance is where most serious-injury claims start. Georgia’s apportionment statute has the jury set each person’s percentage of fault. Each at-fault person then owes only its own share, because the damages “shall not be a joint liability among the persons liable” (O.C.G.A. § 51-12-33-pdf.pdf)-pdf.pdf)-pdf.pdf)).
The statute also says that if you are 50 percent or more responsible, you cannot recover damages (O.C.G.A. § 51-12-33). That bar matters even when you believe the other driver caused the crash. Insurers often look closely at the crash report and witness statements to test who was at fault.
Liability limits can be much lower than the cost of a serious injury. A fracture that needs surgery, or a brain injury that needs long-term care, can cost more than one policy pays. That is why your own coverage deserves a close look.
This guide focuses on serious injuries with real medical treatment. It does not cover minor bumps that never led to care.
If a crash left you with a broken bone, a head injury or a family loss while someone else was at fault, you don't have to sort out the insurance calls alone. Our team can talk it through with you. Talk it through with our team — the first consultation is free, confidential, and carries no obligation.
What Liability Insurance Covers When You Were Not at Fault
The at-fault driver’s liability coverage pays the injured person’s damages, up to the policy’s limits. Bodily injury liability pays for injuries to other people in a crash the insured driver caused. For a serious-injury claim, that can include medical bills, lost income and pain and suffering, within those limits.
Property damage liability pays for your vehicle or other property the at-fault driver damaged. It is a separate coverage with its own limit.
Policies set a per-person limit and a per-accident limit. If several people were hurt, they may share the per-accident amount. A small policy can leave a large injury only partly covered.
Liability coverage is not automatic money. The insurer can dispute how the crash happened or how serious your injury is. Georgia’s avoidance rule also matters. The statute says that if you “could have avoided the consequences to himself caused by the defendant’s negligence” with ordinary care, you are “not entitled to recover” (O.C.G.A. § 51-11-7-2017-pdf.pdf)-2017-pdf.pdf)-2017-pdf.pdf)). Keep that in mind when you talk with the insurer.
Who Pays for What: Liability Coverage Versus Your Own Policy
Liability coverage pays the other side’s losses. Your own policy pays for your vehicle and may pay some of your medical costs.
Collision coverage pays to repair your car, minus your deductible. It works no matter who caused the crash, as long as you carry it.
Medical payments coverage, if your policy includes it, can pay medical bills after a crash. It can apply regardless of fault. Your policy’s declarations page shows whether you have it.
Under O.C.G.A. § 33-7-11-pdf.pdf), uninsured motorist coverage limits are set at the option of the insured, and the statute offers a choice of limits of not less than $25,000 for one person and $50,000 for two or more people in one accident, or limits equal to the liability limits, and it allows the insured to affirmatively choose uninsured motorist limits in an amount less than the limits of liability.
Some policies also offer underinsured motorist coverage. It can help when the at-fault driver has insurance but not enough to cover your losses. Your policy’s wording controls how it works.
Should You File a Claim With Your Own Insurer?
Many people file with their own insurer to get faster payment for a car or medical bills. The choice still has trade-offs to weigh first.
Your insurer may pay first and then seek reimbursement from the at-fault driver’s insurer. This process is called subrogation. It can affect how your claim moves and who handles the recovery.
Filing can also bring out-of-pocket costs. You may pay a deductible, and a claim may appear in your insurance history. Ask your insurer how it treats not-at-fault claims before you file.
Most policies require prompt notice of an accident, even when you were not at fault. Report the crash promptly. A late report can create problems with your coverage.
Getting Your Deductible Back From the At-Fault Driver
You may be able to recover your collision deductible from the at-fault driver or that driver’s insurer. The process depends on who paid for the repairs and how the claim was handled.
Start by gathering your documents. Keep the repair estimate, receipts, the claim number, the police report reference and photos of the damage. These records support any request to repay your deductible.
Keep car costs and medical costs in separate files. Each one has its own claim line and its own paperwork. Mixing them up makes it harder to track what was paid and what is still owed.
If your insurer paid for the repairs, ask how it handles your deductible in any recovery effort. Get the answer in writing when you can.
Dealing With the Other Driver’s Insurance Adjuster
The adjuster works for the at-fault driver’s insurer, so the adjuster is not on your side. Keep that in mind on every call.
Think before you give a recorded statement. Stick to facts you know, and say so when you don’t know something. Don’t guess about speed, distance or timing.
Early offers often come before anyone knows how serious a fracture, brain injury or spinal injury will become. Accepting too soon can be a costly mistake. Ask for time to see your doctor and understand your condition first.
Read every release before you sign it. A signed release can end your claim, so know exactly what it gives up. Keep a log of calls, letters and offers, with dates and names.
Not sure what your next step is?
Talk it through with our team — the first consultation is free, confidential, and carries no obligation.
Medical Bills, Health Insurance and Keeping Records
Georgia limits medical damages to the value of necessary care. The statute says special damages for medical expenses are limited to “the reasonable value of medically necessary care, treatment, or services” (O.C.G.A. § 51-12-1.1-pdf.pdf)-pdf.pdf)-pdf.pdf)). Your records need to show why each treatment was needed.
If you have health insurance, the rules get more detailed. The statute makes relevant both the amounts charged and “the amounts actually necessary to satisfy such charges” under the insurance contract. That is true whether or not you used the insurance (O.C.G.A. § 51-12-1.1-pdf.pdf)-pdf.pdf)-pdf.pdf)).
Some people treat under a letter of protection. That is a promise to pay from any settlement or judgment. The statute makes that letter, itemized charges and any referral relevant and discoverable in a lawsuit (O.C.G.A. § 51-12-1.1-pdf.pdf)-pdf.pdf)-pdf.pdf)).
See a medical doctor for evaluation and follow-up care. Keep every bill, diagnosis, imaging result and work note. Gaps in treatment give the other side something to question, so keep appointments and write down why any gap happened.
Time Limits That Apply Even When You Were Not at Fault
Georgia generally requires lawsuits for injuries to a person to be brought “within two years after the right of action accrues” (O.C.G.A. § 9-3-33-2023-pdf.pdf)-2023-pdf.pdf)-2023-pdf.pdf)). The clock starts when the right of action accrues, a legal term. In many injury cases, that is the date of the crash.
The same statute has other periods for certain claims. It sets one year for injuries to reputation and four years for actions involving loss of consortium. Don’t assume two years applies to every claim.
Insurance policies have their own notice requirements. Those can be shorter than the lawsuit deadline, so a delay in reporting can hurt a claim even when the lawsuit deadline is still far away.
Evidence also fades. Skid marks, camera footage and witness memories all become harder to use over time. Acting early protects the proof you will need.
When a Loved One Has Died: How Insurance Applies to Families
In Georgia, a surviving spouse, or children if there is no surviving spouse, may bring a wrongful death claim. The statute allows recovery for a spouse’s or parent’s death of “the full value of the life of the decedent, as shown by the evidence” (O.C.G.A. § 51-4-2-pdf.pdf)-pdf.pdf)-pdf.pdf)). The statute sets the spouse’s share as well. The spouse “shall receive no less than one-third of such recovery” (O.C.G.A. § 51-4-2-pdf.pdf)-pdf.pdf)-pdf.pdf)).
When death results from criminal or other negligence, the personal representative may recover “the funeral, medical, and other necessary expenses resulting from the injury and death” (O.C.G.A. § 51-4-5-2017-pdf.pdf)-2017-pdf.pdf)-2017-pdf.pdf)).
Families often look at three sources of insurance. These are the at-fault driver’s liability limits, the deceased person’s own coverage, and any uninsured motorist coverage. Each one may apply in a different way, so it helps to gather all of the policies early.
Families also face grief and paperwork at the same time. Keeping the crash report, medical records and funeral bills organized can ease the load.
Commercial Trucks: Different Policies, Different Questions
Federal rules set minimum insurance for many commercial carriers. The federal table lists $750,000 in public liability for for-hire carriers of nonhazardous property in interstate or foreign commerce with a gross vehicle weight rating of 10,001 pounds or more (49 CFR § 387.9). That federal figure is a starting point, not a measure of your claim’s value.
Federal driver qualification rules are in 49 CFR § 391.11, which bar a person from driving a commercial motor vehicle unless he or she is qualified to do so. Records under these rules can matter in a truck crash claim.
The Insurance Institute for Highway Safety publishes fatality facts on large trucks. Those facts can help families understand the risks in these crashes.
A truck crash can involve more than one party, each with its own coverage.
Talk With Ugwonali Law Group About Your Crash
You can talk with Ugwonali Law Group about how insurance applies to your crash, in English or Spanish. The firm handles serious-injury cases in metro Atlanta and across Georgia, including truck crashes, car crashes, wrongful death, traumatic brain injury, spinal cord injury and premises liability.
Frequently asked questions
How does insurance work if it’s not your fault?
The at-fault driver’s liability insurance pays the injured person’s damages, up to its limits. Your own policy may cover your car and some medical bills.
Will insurance still pay if I’m partly at fault?
Georgia reduces damages by your share of fault. You can’t recover damages if you are 50 percent or more responsible (O.C.G.A. § 51-12-33-pdf.pdf)-pdf.pdf)-pdf.pdf)).
How long do I have to file an injury lawsuit in Georgia?
Georgia generally allows two years after the right of action accrues for injuries to a person (O.C.G.A. § 9-3-33-2023-pdf.pdf)).
Does my health insurance pay after a crash I didn’t cause?
Health insurance may pay treatment bills. Georgia law makes the amounts needed to satisfy those charges relevant in a claim (O.C.G.A. § 51-12-1.1-pdf.pdf)-pdf.pdf)-pdf.pdf)).
If a crash has left you or someone you love with a hospital stay, a serious injury or a loss, you don’t have to sort out the insurance on your own. Reach out to our team to talk through your options, in English or Spanish. Request a free case evaluation. The first consultation is free, confidential, and with no obligation to continue (Spanish: consulta inicial gratuita, confidencial y sin compromiso).
Responsible attorney: Adanna Ugwonali, Ugwonali Law Group, 3400 Peachtree Road NE, Atlanta, Georgia.
Attorney advertising. This page is general information and is not legal advice. Results depend on the facts of each case, and no outcome is promised.
What Shapes Your Insurance Picture
The at-fault party's liability insurance
When another driver, a trucking company, or a property owner caused the harm, that party's liability insurance is usually the first place a claim is made.
Your own policy
Your own auto policy may include medical payments or other coverage that applies to your car and some of your medical bills.
Your medical treatment
Records from your doctors, hospital, and therapists help show what you were treated for and what care you still need.
Families in wrongful death cases
When a loved one dies, the questions about insurance, the claim, and who may bring it can be complicated. Families do not have to sort them out alone.
Be Careful With Early Calls
Insurance adjusters work for the insurance company, not for you. Speak with a lawyer before you give a recorded statement, accept a settlement offer, or sign any release.
Questions to Bring to Your First Call
Who was insured?
Tell us who was driving or responsible for the property, and which company insured them, if you know.
What treatment have you had?
Hospital visits, imaging, surgery, and follow-up care all help explain the full impact of your injury.
Have you talked with an insurer?
Share any letters, calls, or forms you received so we can review them with you.
Do you have your records?
Keep the police report, photos, bills, and work notes. Our team can help you gather what is needed.