Slip and Fall · Atlanta and Georgia
When a Fall on Someone Else's Property Leaves You Hurt, Commercial Insurance May Be Part of the Picture
Ugwonali Law Group helps people injured in slip and falls on commercial property across metro Atlanta and statewide Georgia understand how liability insurance works and what the legal process involves. Your first consultation is free, confidential, and comes with no obligation to continue.
Getting Started With Our Office
Free
Confidential first consultation with no obligation
EN / ES
Intake in English or Spanish
Georgia
Serving metro Atlanta and statewide
By Adanna Ugwonali · Published October 18, 2026
In many Georgia slip and fall cases, the injured person’s claim is made against the property owner, and the owner’s liability insurance is often the source of payment. This guide explains how a commercial liability insurance slip and fall claim usually works in Georgia. It covers policy limits, time limits, fault sharing, and the early steps that matter most. Ugwonali Law Group is a personal injury firm in Atlanta, Georgia, led by attorney Adanna Ugwonali.
Who Pays After a Slip and Fall in Georgia: The Short Answer
In many premises cases, the property owner’s liability insurance is the source of payment for an injured visitor’s claim. Georgia law sets the owner’s basic duty. Under O.C.G.A. § 51-3-1-2017-pdf.pdf)-2017-pdf.pdf)-2017-pdf.pdf)-2017-pdf.pdf), an owner or occupier who invites people onto the property for a lawful purpose is liable for injuries caused by failure to exercise ordinary care in keeping the premises and approaches safe.
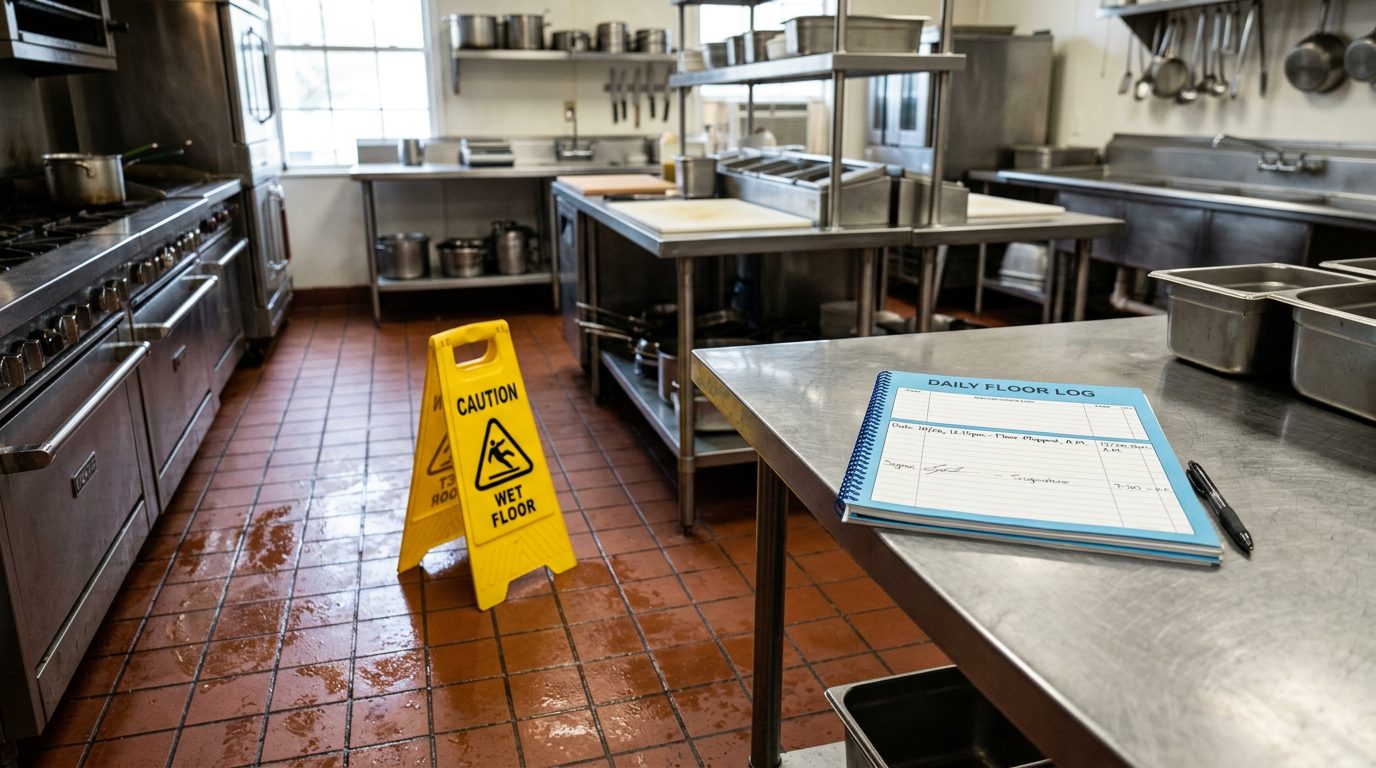
In plain words, an owner or occupier of land who invites or leads others onto the premises for any lawful purpose must use ordinary care in keeping the premises and approaches safe for them, such as floors, walkways, parking areas, and entrances. A fall on a wet floor, a broken step, or an uneven parking lot can raise this question.
Whether a particular claim succeeds depends on the facts. Key questions include who controlled the area, what caused the fall, and what the injured person was doing at the time. Those answers shape how the case is built.
If a fall on someone else's property left you with a fracture, a hospital stay, or a spinal or brain injury, we can help you sort out which insurance may apply. Our first consultation is free and confidential. Talk it through with our team — the first consultation is free, confidential, and carries no obligation.
How a Commercial General Liability Policy Responds to Premises Claims
In a commercial liability insurance slip and fall case in Georgia, the business’s commercial general liability (CGL) policy is usually the first place to look. A CGL policy is the main insurance most businesses carry for bodily injury claims tied to their premises and operations.
When a covered bodily injury claim arises on a business’s property, the CGL policy generally responds. That response is subject to the policy’s terms, exclusions, and conditions. The claim is made against the policyholder. The insurer may then defend the claim and pay covered amounts, up to the policy limits.
An injured visitor often doesn’t see the policy at the start. The insurer’s identity may come out through the claim process, the business, or the property manager. The policy’s wording controls what is covered, so identifying the right policy early helps.
Policy Limits: Per Occurrence, Aggregate, and Why the Available Amount Can Be Less Than the Full Value of a Serious Injury
A policy limit is the most the insurer will pay under the policy. Limits are often described in two ways. A per-occurrence limit is the most the policy pays for one incident. A general aggregate limit is the most it pays across a single policy period.
Serious injuries can carry large losses. Fractures, hospital stays, brain or spinal injuries, and death create medical bills, lost income, and long-term care needs. The policy’s limits are set by the coverage the business bought. Available coverage may fall short of those losses.
Other claims under the same policy in the same period can use up part of the limits. A claim’s value and the amount a policy will pay are different things. Knowing the limits early helps set realistic expectations about what is available.
Umbrella and Excess Policies: Additional Layers of Coverage
An umbrella or excess liability policy adds coverage above a primary CGL policy. It generally applies after the primary limits are used up. Not every business carries one, and the terms vary by policy.
Whether a business has an umbrella policy, and what it covers, depends on the policy and the business’s coverage choices. An injured person often doesn’t know at first whether an extra layer exists. Asking early about the full insurance picture is practical.
These layers can matter most in serious cases, where the primary limits may not cover every loss. Documenting the fall and the injury clearly helps the claim move forward. Records should show what happened, where, and how the injury has affected daily life.
Georgia Minimum Liability Insurance: Auto Rules Versus Business Policies
This is a motor vehicle rule. It doesn’t set the limits of a business premises policy. A business’s general liability limits come from its own policy and the coverage it chose.
Why does this matter? Someone searching for minimum insurance figures may find auto numbers. Those answer a different question. For a slip or trip on a store floor, the business’s CGL policy and its limits are the questions to ask.
Time Limits: The Two-Year Rule and Why Early Steps Matter
Georgia generally gives two years from the date of injury to bring an action for injuries to the person. Under O.C.G.A. § 9-3-33-2023-pdf.pdf)-2023-pdf.pdf)-2023-pdf.pdf)-2023-pdf.pdf), that is the general rule. The same statute sets four years for certain loss of consortium claims, so the statute has exceptions.
Wrongful death follows its own rules. Under O.C.G.A. § 51-4-2-pdf.pdf)-pdf.pdf)-pdf.pdf)-pdf.pdf), a surviving spouse, or if there is none, a child or children, may recover the full value of the decedent’s life, as shown by the evidence. Families facing these questions should review them promptly. You can read more on our wrongful death page.
Early steps help too. Identifying the at-fault property’s insurer early helps keep evidence in place. That evidence includes incident reports, surveillance video, maintenance logs, and witness contact information.
Not sure what your next step is?
Talk it through with our team — the first consultation is free, confidential, and carries no obligation.
Fault Can Be Divided: Multiple Parties and How Responsibility Is Shared
Georgia divides fault by percentage. More than one party may share responsibility for a fall. Examples include the property owner, a management company, a contractor who did recent repair work, or a tenant. Each may have its own insurance.
Under O.C.G.A. § 51-12-33-pdf.pdf)-pdf.pdf)-pdf.pdf)-pdf.pdf), the jury determines the injured person’s percentage of fault, and the judge reduces the damages in proportion. Damages are then divided among the liable parties by each party’s percentage of fault. Each party pays its own share, and the shares are not joint. The statute also says that a plaintiff who is 50 percent or more responsible for the injury is not entitled to any damages.
Georgia’s rule on avoidable harm also matters. Under O.C.G.A. § 51-11-7-2017-pdf.pdf)-2017-pdf.pdf)-2017-pdf.pdf)-2017-pdf.pdf), if the plaintiff by ordinary care could have avoided the consequences of the defendant’s negligence, the plaintiff cannot recover. In other cases, the defendant is not relieved just because the plaintiff contributed in some way. The facts of the fall decide how these rules apply. See our premises liability overview for more.
Steps to Take to Identify the Policy After a Serious Fall
The most useful steps after a serious fall are to record facts and keep medical records. Gather these items as soon as you can:
- The property’s name, address, and owner or manager
- Photos of the hazard and the area around it
- Names of staff members and witnesses
- The incident report, if one was made
- All medical records, bills, and treatment notes
- A written log of symptoms, treatment, and time missed from work
A claim adjuster may contact an injured person early. Before giving a recorded statement or accepting an early offer, it helps to understand what is being asked and what is being given up.
The OSHA walking-working surfaces standards offer one benchmark for what safe walking surfaces look like.
Frequently Asked Questions
Does a store’s liability insurance pay for a slip and fall?
Often, the claim goes to the business’s liability insurer, subject to the policy’s terms and limits.
Is there a time limit to bring a personal injury claim in Georgia?
Under O.C.G.A. § 9-3-33-2023-pdf.pdf)-2023-pdf.pdf), except as otherwise provided in this article, actions for injuries to the person shall be brought within two years after the right of action accrues, except for injuries to the reputation, which shall be brought within one year after the right of action accrues, and except for actions for injuries to the person involving loss of consortium, which shall be brought within four years after the right of action accrues.
What if I was partly at fault for a commercial liability insurance slip and fall in Georgia?
Georgia reduces damages by your percentage of fault, and you cannot recover if you are 50 percent or more responsible (O.C.G.A. § 51-12-33).
Talk With Ugwonali Law Group About Your Fall at 3400 Peachtree Road NE
If you fell in a store, a parking lot, or a poorly kept building and suffered a fracture, hospital care, or a brain or spinal injury, you may be unsure which insurer should respond. You may also wonder whether the available limits can cover your losses. Attorney Adanna Ugwonali at Ugwonali Law Group, 3400 Peachtree Road NE, Atlanta, Georgia, can review those facts with you. Request a free case evaluation today. The first consultation is free, confidential, and without obligation to continue. Intake staff can assist in English or Spanish, and Spanish-speaking readers will see this described as “consulta inicial gratuita, confidencial y sin compromiso.”
How We Approach Your Slip and Fall Claim
Gathering the Facts
We help you record what happened, where, and when, and we discuss the incident reports, photographs, and witness details that often matter in a premises case.
Connecting Your Medical Care
Fractures, head injuries, and back injuries need proper treatment by a medical doctor. We explain how your records and treatment history fit into your claim.
Understanding the Insurance Side
We explain how commercial liability policies work in general terms, including why the property owner's insurer may be involved, so you know what to expect.
Explaining Each Step
Our team walks you through the legal and medical process in plain language, so you can make informed decisions at every stage.
Act Promptly to Protect Your Information
Evidence from a fall, such as photos, witness names, and surveillance footage, can change or disappear over time. Keep your medical records, receipts, and any paperwork from the property owner, and avoid giving recorded statements to insurance adjusters before you have spoken with a lawyer.
What to Bring to Your Free Case Review
Medical Records
Emergency room notes, imaging results, discharge papers, and bills from every provider who treated your injuries.
Incident Details
A written account of the fall, the location, the time, and the conditions, such as spills, lighting, or missing warning signs.
Photos and Witnesses
Pictures of the hazard and the scene, along with names and phone numbers of anyone who saw what happened.
Property Information
The business or property owner's name and any paperwork you received, such as an incident report or a letter from an insurer.